
[This article is exclusive to GoldenMeadow.eu and GoldPriceForecast.com – based on today’s Gold Trading Alert]
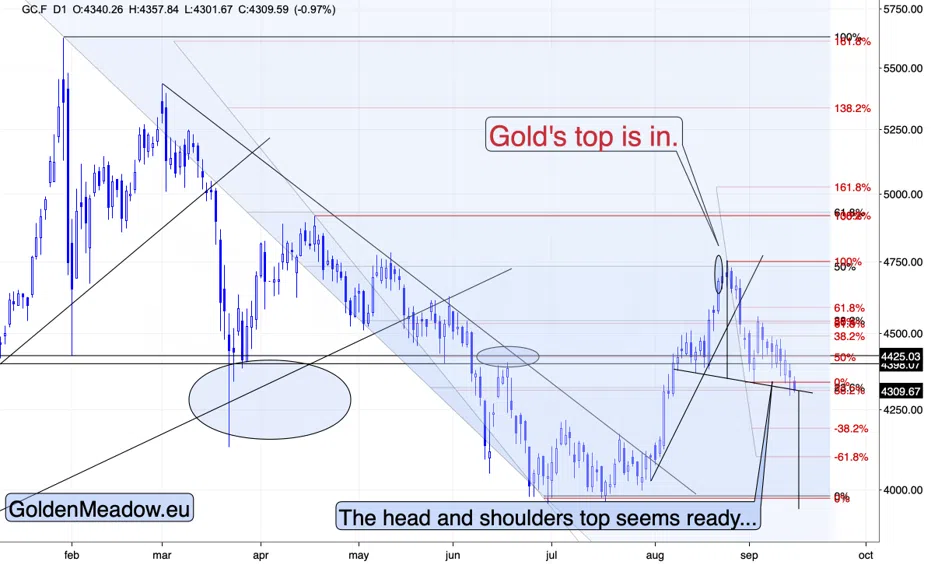
The FOMC opens its meeting today with a hike 92 percent priced, the 10-year yield at 5.04 percent this morning, its highest since 2007, and Brent crude near $107.50 with the Saudi bypass pipeline still shut. Gold settled Monday at $4,351.90, down 1.3 percent, and trades near $4,309 as I write this.
That is the neckline, to the dollar. Not below it. At it.
The Market Has Already Hiked
The two-year yield is near 4.65 percent, the 10-year crossed 5 percent on Monday for the first time since October 2023 and went through it again overnight to a level last seen before the financial crisis, and the 30-year is at 5.33 percent. Goldman Sachs, which sees limited fundamental justification for tightening, now expects a hike anyway, on the grounds that the FOMC "will likely want to avoid the market reaction that would likely follow from remaining on hold." Read that carefully. The bank's argument for a hike is not inflation. It is that the market has priced one so completely that not delivering would be the shock.
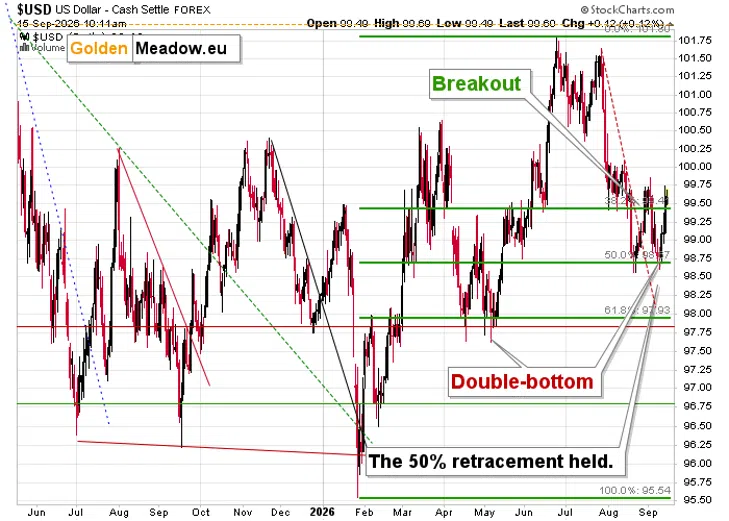
So the Fed meets to ratify what the bond market has already done, and that is why the dollar advanced on Monday and is higher again this morning while the yen sits at a seven-month high. The rate channel that has driven gold since Jackson Hole is no longer a forecast. It is the tape.
Wednesday's Four Outcomes
The decision arrives at 2 p.m. Eastern tomorrow with the dot plot, and Chair Warsh's press conference follows. Here is how I see each outcome and what it would do to the setup.
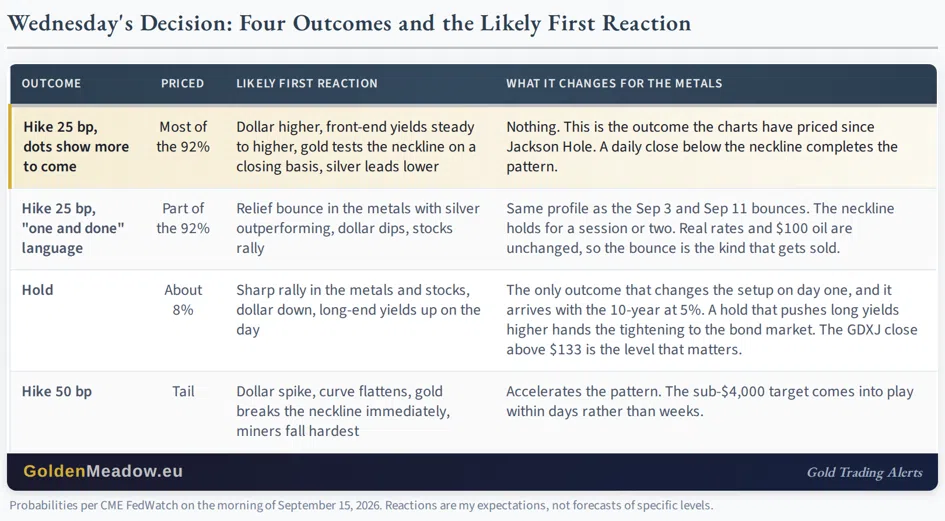
The row that deserves a second look is the hold. It is the only result that changes the picture on day one, and it would arrive with the 10-year at 5 percent and oil above $100. A Fed that holds in those conditions does not end the tightening. It hands the tightening to the bond market, which has shown for three weeks that it will do the job without waiting. That is why the level that matters in that scenario is the GDXJ's daily close above $133, not the size of the first-hour rally.
At The Line
Yesterday, I wrote: "Given today's pre-market decline in gold, I expect the GDXJ to decline as well."
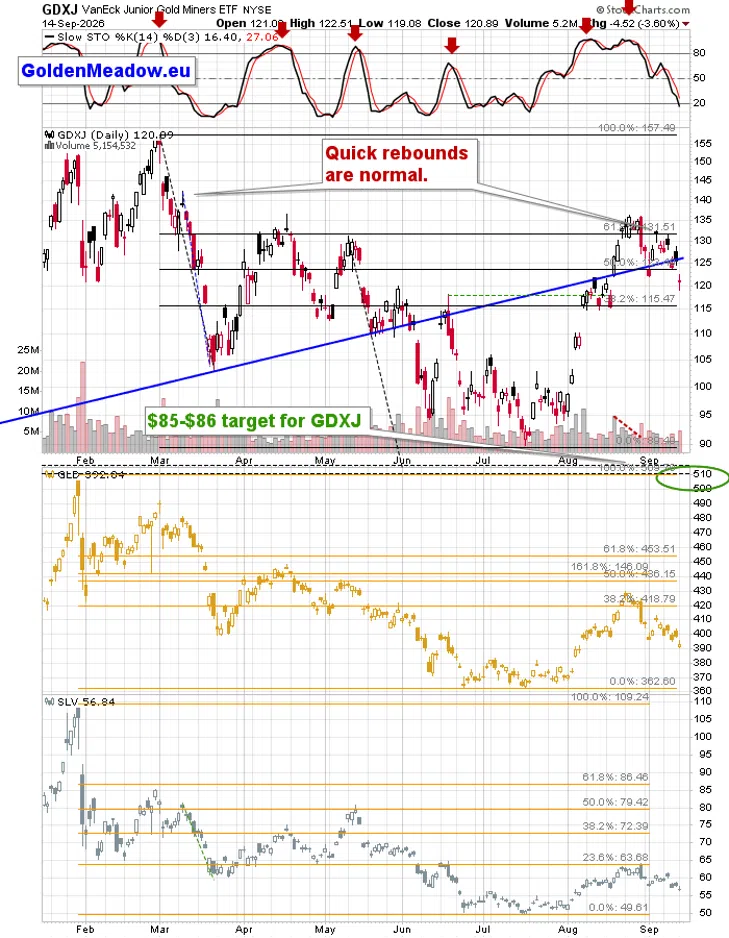
It did, with silver and gold miners across the board falling on Monday, and gold has now reached the neckline of the head-and-shoulders top that I have been describing since September 4. It is sitting on the line this morning rather than below it, which is exactly the place a pattern like this one waits for its catalyst, and the catalyst is scheduled. A daily close below the line completes the formation, with the target below $4,000.
Silver settled Monday at $64.14, down 1.6 percent, and is lower again this morning, below $64. Yesterday I noted that silver had already completed its own head-and-shoulders top and was sitting on the declining support line that stopped the late-August decline. It is still there, and the two metals are now testing their lines together, a day before the Fed.
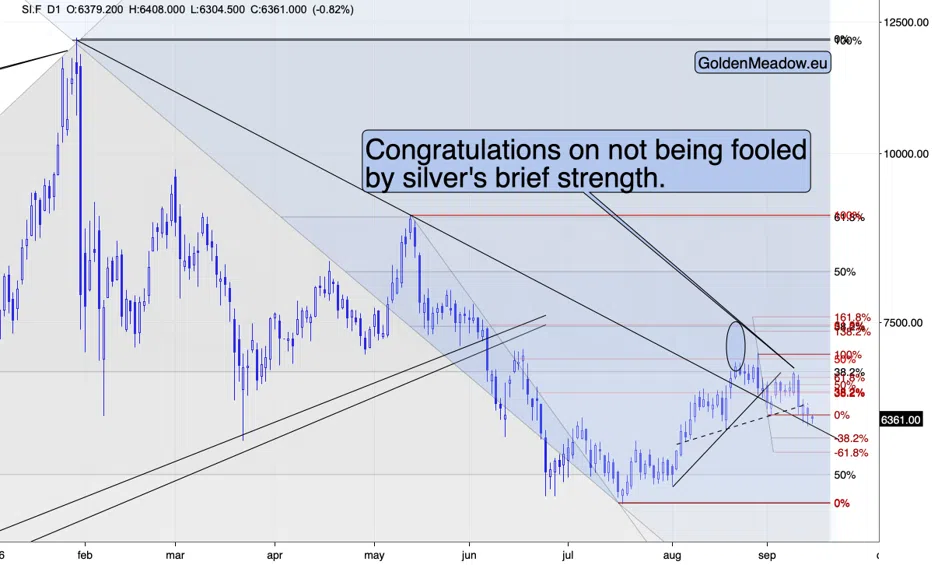
Breakdowns’ aftermath could be brutal for the longs. Whether it happens around the decision rate is not clear. What is clear to me is that this is the most likely outcome, anyway.
Two Chokepoints And A Pipeline
The oil side of the rate channel did not pause for the meeting.
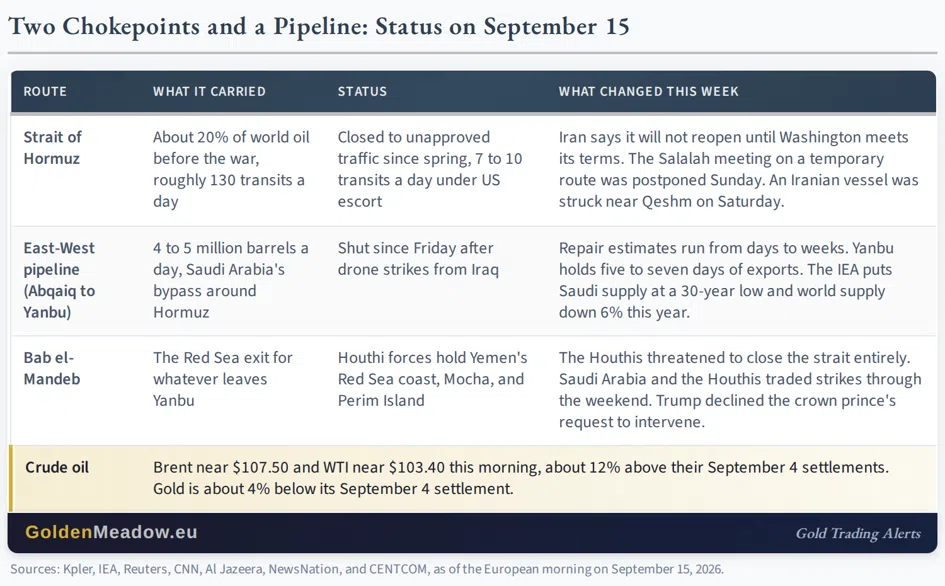
The detail that matters most is the five-to-seven days. That is how long Saudi traders say the stocks at Yanbu will sustain exports with the East-West pipeline shut, and the pipeline has been shut since Friday, with repair estimates that run from days to weeks. After that, as much as 4 percent of world supply is at risk on top of what Hormuz has already taken out. Iran, for its part, said it will not reopen the strait until Washington meets its conditions, Saudi Arabia submitted amendments to the Omani plan that helped stall the Salalah meeting, and Bahrain had said it would not attend.
Crude is up about 12 percent since September 4. Gold is down about 4 percent over the same period. That is the relationship in one line, and it is the reason Wednesday's decision is a hike and not a hold.
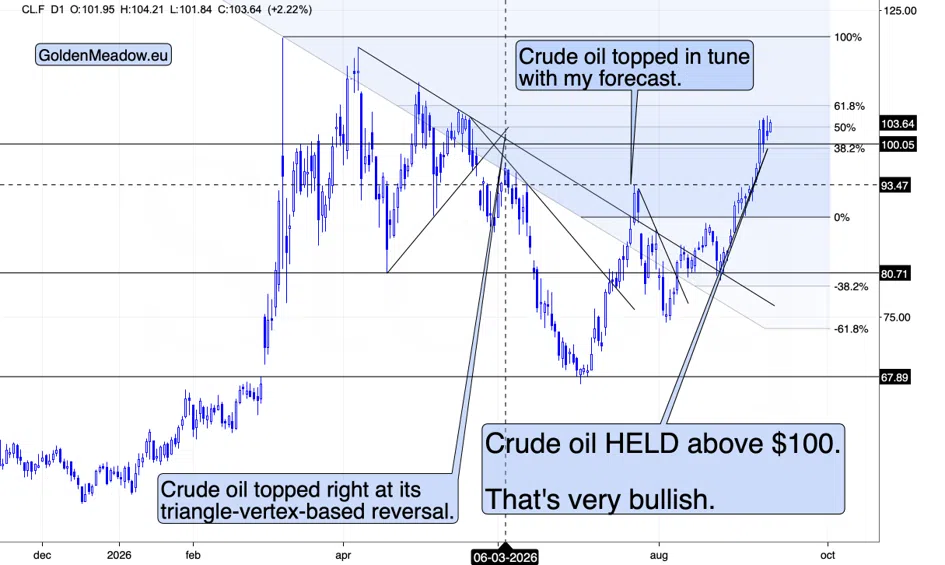
Technically, crude oil verified its breakout above $100 – it’s well-positioned to soar once again.
Washington's Full-Court Press
The president, the vice president, the Treasury secretary, and a senior economic adviser have all publicly urged the Fed not to hike, and on September 4 the president threatened to halt trade with countries that run surpluses with the United States unless the Fed cuts, writing that the board "must get smart – BE PATRIOTS for a change." Chair Warsh's answer, delivered at Jackson Hole before any of it, was that "we must be confident that underlying inflation is moving to our objective, clearly and at sufficient speed. Otherwise, we have work to do."
Last week I laid out why the argument that politicians would hold markets up into the midterms fails on the data. This week it is failing on the calendar. The White House wanted the war quiet and rates low into November. It is getting a second closed chokepoint and a hike from its own chairman.
Stocks: The AI CEOs Want A Culprit
The S&P 500 fell 0.48 percent on Monday to 7,619.98, back below the June high it had recovered on Friday, the Nasdaq lost 0.56 percent, and the Philadelphia Semiconductor Index fell about 5 percent, its worst day since early July. Futures are lower again this morning with the 10-year above 5 percent.
The trigger was a 3,800-word essay. On Saturday, Anthropic's chief executive published "We Must Pace the Frontier," arguing that the leading AI labs should deliberately slow the rate at which they improve their models to let safety work catch up, and within a day OpenAI's Sam Altman, Elon Musk, and Google DeepMind's Demis Hassabis had publicly agreed with him. Altman added that OpenAI would not go public in 2026 after all, telling Fortune that "given everything happening with safety, right now would be an ill-advised moment." President Trump rejected any slowdown on Sunday, citing China. The market rejected the stocks.
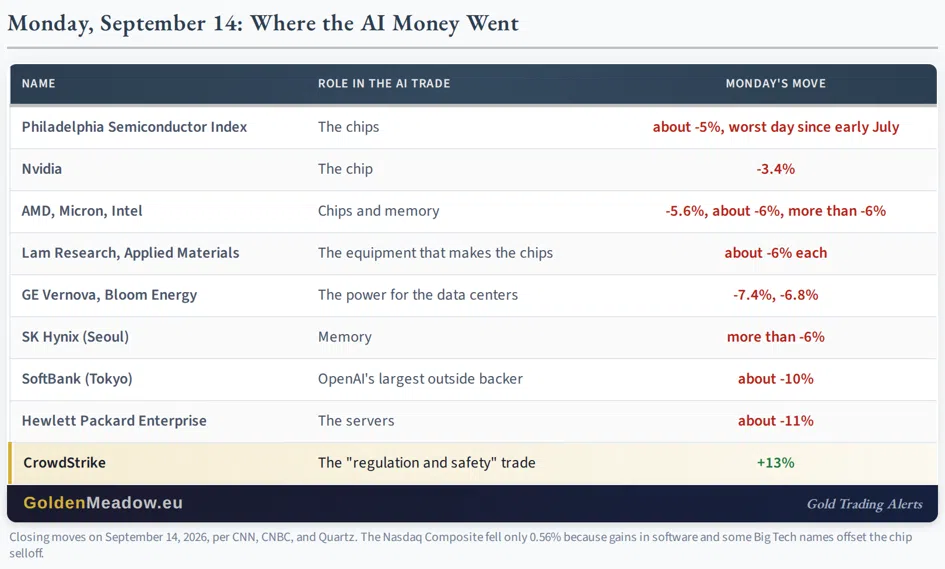
Here is how I read it, and I want to be clear that this is my interpretation of the timing rather than a claim about anyone's motives.
The people who run the three companies that set the pace of this technology have, in the same weekend, discovered that the pace is too fast. None of them announced a change to their own release schedules, training budgets, or product roadmaps. What they announced was a reason.
And the reason arrived at a specific moment: with the S&P 500 at its highs and 36 percent technology by weight, the four largest hyperscalers having spent about $560 billion on AI infrastructure over two years against roughly $35 billion of AI revenue, Bain estimating the industry needs $2 trillion a year by 2030 and will fall $800 billion short, and Oracle guiding to $90 to $95 billion of capital spending this year.
The valuations require a growth curve that the capital expenditure cannot produce.
When that becomes visible, the growth curve bends, and every bent growth curve needs an explanation that is not "we were priced for something we cannot deliver."
"Necessary regulation" is that explanation. It is external, it is virtuous, and it cannot be argued with in a shareholder letter. Whether or not that is anyone's intent, it is the effect, and the market priced the effect on Monday: chips and the power and server companies that feed the buildout fell 5 to 11 percent, and the one stock that rose 13 percent was the cybersecurity name that benefits from the regulation. The company that was going to hold the largest IPO in history has decided not to, and the reason it gave was safety, not price.
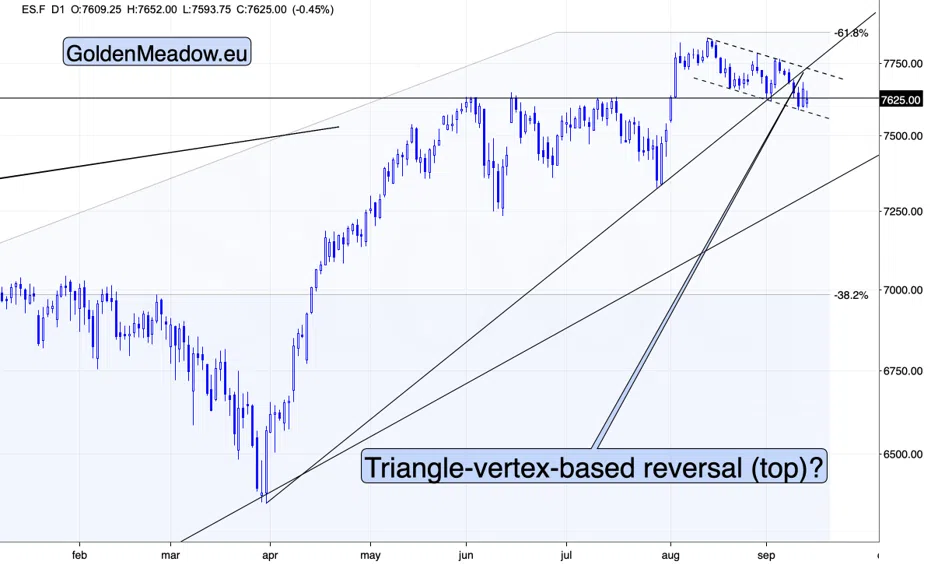
Yesterday I wrote that the upper border of the declining channel and the rising medium-term resistance line crossed on Monday, and that the triangle-vertex-based reversal technique pointed to a top. Friday's close at 7,656 is the high so far, Monday moved away from it, and the sector that led the market up is the sector that led it down. One session above the June high, on the largest large-cap fund outflow on record, followed by the AI complex's worst day in two months, is what a takeout looks like from the inside.
The implication for us runs through the 2008 sequence I showed on September 9. When the stock market's leadership breaks, the decline does not stay in the leadership. Industrial commodities get sold as growth assets, silver gets sold as an industrial metal, gold gets sold as collateral, and mining stocks get sold as equities first and as gold proxies second, which is why the GDX in 2008 fell further than either gold or the S&P 500.
A stock market topping on a bursting AI bubble, with the Fed hiking into it and oil above $100, is not a rotation into the metals. It is the liquidation setup, and Monday's session, with miners down more than gold and copper down with the chips, was a small rehearsal of it.
The Calendar
August retail sales arrive at 8:30 a.m. Eastern today, the Fed decides tomorrow at 2 p.m. with the press conference at 2:30, the Bank of England decides Thursday along with the Security Council vote on Iran sanctions, the BoJ decides Friday with a hike expected, and Friday is quadruple witching.
Where This Leaves Us
My outlook and positions are unchanged, and the profit-take levels remain in place.
Gold is at the neckline and silver at its support line on the day the Fed begins the meeting that the bond market has already decided, with the 10-year at a 19-year high, oil at $107, the dollar rising into it, and the stock market's leadership breaking on the word of the people who run it. The pattern needs one close. The calendar provides one tomorrow.
The market is not waiting for the Fed to tell it what rates are. It is waiting for the Fed to agree.
Thank you for reading the free version of today’s analysis. I encourage you to subscribe for the premium version today. If you’re not ready to subscribe yet, I encourage you to sign up for my free gold newsletter now.
Thank you.
Sincerely,
Przemysław K. Radomski, CFA